
DISH DBS Corporation
Charlie Ergen-Backed EchoStar Units Emerge from Chapter 11 on October 1st Following $4.75bn Deleveraging, Completing DBS Side of Bifurcated Prepack as DISH Wireless Cases Continue
by Nick Montgomery | Oct 2, 2026, 9:47:50 AM
October 1, 2026 – The DISH DBS Debtors notified the Court that their standalone Second Modified Joint Prepackaged Chapter 11 Plan became effective and was substantially consummated on October 1st, two days after confirmation and 93 days after their June 30th Chapter 11 filing [Docket No. 1689]. Judge Christopher M. Lopez had confirmed the Plan and approved the related Disclosure Statement on a final basis on September 29th [Docket No. 1649].
Effectiveness applies only to the DBS Debtors and does not conclude the jointly administered Chapter 11 cases. What began as a single prepackaged restructuring for the DBS and DISH Wireless Debtors was bifurcated in late August after the Debtors elected to litigate disputed Wireless tower claims on the merits before confirmation, allowing DBS to proceed separately while the six DISH Wireless Debtors remained in Chapter 11. The now-effective DBS Plan reduces aggregate DBS funded obligations from approximately $9.75bn to $5.0bn through repayment and redemption of the 2026 maturities and amended treatment of the remaining 2028 and 2029 notes, while reinstating DBS general unsecured claims and existing equity.
The DBS Debtors were represented by: (i) White & Case LLP as bankruptcy counsel, (ii) Quinn Emanuel Urquhart & Sullivan, LLP as special litigation and conflicts counsel, (iii) Redgrave LLP as discovery counsel, (iv) Steptoe LLP as special regulatory and litigation counsel, (v) FTI Consulting, Inc. as financial advisor, (vi) FTI Capital Advisors, LLC as investment banker and (vii) Epiq Corporate Restructuring, LLC as claims agent.
The deadline for filing professional fee claims has been set for November 16, 2026.
Whether by design or coincidence, the docket itself supplied an immediate reminder that effectiveness of the DBS Plan falls well short of the unified restructuring the Debtors envisioned when they filed 93 days earlier. The DBS effectiveness notice was filed at Docket No. 1689; immediately alongside it, at Docket No. 1688, the Committee filed a statement concerning intervention in the DISH Wireless Debtors’ Tower Claims litigation. That filing supports efforts by Comcast and Cablevision Lightpath to participate in the litigation against Crown Castle, American Tower and SBA and argues that the Wireless Debtors’ force majeure and frustration-of-purpose defenses may affect creditors across the failed 5G network. The Committee warns that rulings on those common defenses could have preclusive consequences for other 5G Network Claimants and proposes a protocol allowing similarly situated creditors to participate in common discovery and briefing. Whatever the reason for the timing, the juxtaposition is difficult to miss: DBS has emerged following confirmation of its bifurcated Plan, while the Wireless Debtors remain in Chapter 11 facing a potentially widening claims fight, leaving the jointly administered cases as a whole far from concluded.
The next scheduled milestone is an October 2nd status conference at which Lopez is expected to assess negotiations and determine the path forward for the Wireless cases, including scheduling of the Committee’s trustee, standing and related motions. Hearings on the Committee’s standing and motion-to-compel requests had been tentatively preserved for October 7th and 8th, while the Tower Claims and intercompany-loan litigation remain slated for later in the fall subject to further scheduling.
Case Summary
The September 29th confirmation of the DISH DBS Plan closes one branch of a restructuring that began 91 days earlier as a single joint prepackaged Chapter 11 for 18 EchoStar subsidiaries but progressively split into two very different cases. When the Debtors filed on June 30th, the proposed structure paired a largely negotiated DBS balance-sheet restructuring with a DISH Wireless liquidation, and the Debtors initially sought an August 17th combined Disclosure Statement and confirmation hearing and emergence before the end of the third quarter. The DBS side entered bankruptcy with an RSA supported by holders of approximately 88.3% of $9.75bn of notes; the Wireless side, by contrast, entered with billions of dollars of disputed tower, fiber and vendor liabilities, an EchoStar stalking horse sale, an $85.0mn EchoStar DIP and no comparable prepetition consensus among its operating creditors.
The DBS filing itself was driven by both long-term deterioration in the Pay-TV business and an immediate maturity problem. DISH had lost approximately 7.3mn net Pay-TV subscribers from its 2014 peak as cord-cutting, streaming competition and rising programming costs compressed the business, while a failed DirecTV transaction and litigation over prior liability-management transactions limited refinancing options. The immediate catalyst was $2.0bn of unsecured notes maturing July 1st, one day after the filing, before EchoStar’s approximately $23.0bn spectrum sale to AT&T had closed and provided the expected liquidity. The March 19th RSA resolved the bondholder litigation, restored subscribers and Sling entities to the DBS credit group and contemplated reducing DBS funded debt from $9.75bn to $5.0bn through repayment of the 2026 maturities and amended treatment of the 2028 and 2029 notes.
The AT&T closing on July 28th materially improved the DBS position while sharpening the dispute over Wireless. DNC paid DBS approximately $2.845bn plus interest on an intercompany loan using AT&T proceeds, allowing DBS to repay the $2.0bn of 7.75% Senior Notes due 2026 immediately. By confirmation, the Debtors also reported that they had redeemed $2.35bn of the $2.75bn of 2026 Senior Secured Notes. The remaining 2028 Senior Secured Notes, 2028 Senior Notes and 2029 Senior Notes continue under amended indentures, while DBS general unsecured claims and equity are reinstated. The economic contrast was increasingly stark: DBS had a contractual path into AT&T-related liquidity and was using it to deleverage, while the Wireless Debtors maintained that they had no claim to the broader AT&T or SpaceX spectrum-sale proceeds because the licenses were owned by EchoStar and other non-Debtor affiliates.
That distinction became the organizing fight in the Wireless cases. The Wireless Debtors had built and operated EchoStar’s facilities-based 5G network using spectrum they did not own and, after FCC pressure led EchoStar to sell key licenses to AT&T and SpaceX, asserted that the resulting loss of spectrum excused continued performance under thousands of tower and infrastructure contracts. Crown Castle, American Tower and SBA ultimately asserted liquidated claims of approximately $4.69bn, $2.7bn and $194.0mn, respectively, plus additional unliquidated amounts. At the same time, creditors challenged an approximately $8.856bn intercompany claim against DWLLC that had been assigned shortly before bankruptcy to a claims trust for the benefit of certain DBS noteholders. The Committee argued that the claim and trust structure were designed to give an insider-originated obligation voting power in Wireless’s sole impaired class; the Debtors disputed that characterization and maintained that the claim should participate like other Wireless general unsecured claims.
The original “prepackaged” timetable began breaking down almost immediately. On July 23rd, Judge Christopher M. Lopez conditionally approved the Disclosure Statement and solicitation procedures but rejected the Debtors’ proposed August confirmation schedule and required votes cast on account of the disputed intercompany claim to be separately tabulated pending litigation over its validity and voting status. The July 30th FCC order then changed the Debtors’ Wireless strategy by excluding the DWLLC Intercompany Loan Claim and other EchoStar-affiliate claims from the approximately $2.4bn FCC Trust. That left the Debtors arguing that, if the Tower Claims could be disallowed or sufficiently reduced, the FCC Trust might be large enough to pay eligible third-party Wireless claims in full. Creditors countered that the theory depended on the Debtors prevailing on billions of dollars of claim objections and did not resolve the broader dispute over value retained outside the Wireless estates.
By August 19th, Lopez forced the Debtors to choose between preserving an accelerated confirmation schedule and obtaining merits rulings on the Tower Claims first. The Court offered two tracks: rely on stipulated claim amounts for voting and continue toward a November confirmation, or conduct fuller discovery and litigate the claims before confirmation, pushing the Wireless process into December. On August 27th, the Debtors chose the merits track. That decision formally bifurcated what had been filed as a single prepackaged restructuring: DBS would proceed separately to protect its ability to emerge before the October 28th outside date under the RSA, while Wireless would remain in Chapter 11 for a longer claims and liquidation process.
Bifurcation did not end the Wireless disputes; it intensified them. On September 6th, the Committee sought appointment of a chapter 11 trustee for the six Wireless Debtors or termination of exclusivity so it could propose its own liquidating Plan, and separately challenged White & Case’s retention as Wireless bankruptcy counsel. The U.S. Trustee later joined the White & Case challenge, although it did not seek a chapter 11 trustee. The Committee’s complaints centered on governance and transactions involving EchoStar and related parties, including the Boost Mobile transfer, the DWLLC Intercompany Loan and Claims Trust, the EchoStar DIP and the proposed stalking horse acquisition of Wireless assets. DBS opposed the trustee and exclusivity relief, arguing that the intercompany claim is an important source of potential recoveries for its noteholders and that changing control of the Wireless cases would add cost and disruption.
The Wireless Debtors responded on September 12th with a substantially revised standalone Plan. Rather than selling estate causes of action to EchoStar under the stalking horse structure, the Plan preserves related-party claims for a three-member Special Governance Committee whose initial members would be selected by the Creditors’ Committee in consultation with the DWLLC Special Committee. It also removes the disputed DWLLC Intercompany Loan Claim from voting absent a court-approved settlement and adds FCC Trust-based Quick Pay alternatives for eligible creditors. Those revisions did not produce creditor support. At the September 14th status conference, the Committee said it did not support the Plan as filed, Crown Castle likewise remained opposed and Lopez imposed a two-week standstill through October 1st to give the parties an opportunity to negotiate before resuming the trustee, standing, Tower Claim and other litigation.
DBS, meanwhile, finally returned to something closer to the consensual restructuring contemplated at the outset. The standalone DBS Plan filed September 4th preserved the core RSA economics while separating DBS from the unresolved Wireless litigation, and Lopez conditionally approved the DBS Disclosure Statement on September 17th. By the September 23rd voting deadline, more than 98% in number and 99% in amount of claims voting across the four impaired DBS note classes had accepted the Plan. All 14 formal objections were resolved before confirmation, and the Committee ultimately supported the DBS Plan after revisions protecting the continuing rights of DBS general unsecured creditors and ensuring that the Wireless estates were not affected by DBS confirmation.
Lopez confirmed the DBS Plan on September 29th and waived the 14-day stay, with the Debtors targeting emergence by October 1st. Confirmation therefore delivers the DBS restructuring roughly three months after a filing originally presented as a joint prepack intended to move through Chapter 11 quickly, but only after the combined structure was abandoned and DBS was insulated from the litigation consuming the Wireless cases. The resulting picture is no longer one restructuring with two business groups: DBS has reached confirmation of a supported deleveraging and refinancing, while DISH Wireless remains in Chapter 11 with unresolved Tower Claims, governance and professional-retention disputes, litigation over the $8.856bn intercompany claim and continuing negotiations over whether its amended liquidation Plan can attract enough third-party creditor support to reach confirmation at all.
Plan Overview
The confirmed DBS Plan implements the DBS portion of the March 19th RSA on a standalone basis following the separation of the DISH Wireless cases from the original joint prepackaged restructuring. The Plan carries forward the principal DBS economics negotiated before bankruptcy—repayment of the 2026 maturities, amended treatment of the 2028 and 2029 notes, reinstatement of general unsecured claims and existing equity, and the settlement and releases negotiated with consenting noteholders—while expressly leaving the DISH Wireless estates, their claims and the disputed DWLLC Intercompany Loan Claim to the separate Wireless cases. Each DBS Debtor emerges separately, without substantive consolidation, with Plan distributions funded through cash on hand and amended DBS notes.
The RSA was supported before bankruptcy by holders of more than 88% of the aggregate principal amount of DBS notes, and the restructuring is designed to reduce DBS funded obligations from $9.75bn to $5.0bn as the 2026 maturities are retired. By confirmation, a substantial portion of that deleveraging had already occurred:
- The $2.0bn of 7.75% Senior Notes due 2026, together with accrued and unpaid interest, was paid in full on July 28th, eliminating Class 1E from the operative Plan.
- The DBS Debtors subsequently redeemed $2.35bn of the original $2.75bn of 5.25% Senior Secured Notes due 2026, leaving approximately $400.0mn of principal outstanding. Holders of any remaining allowed Class 1C claims receive Amended 2026 Senior Secured Notes corresponding to unpaid principal, together with cash for accrued interest and other amounts due under the applicable indenture.
- The approximately $2.5bn of 2028 Senior Secured Notes remain outstanding as amended notes, with accrued interest and other amounts due paid in accordance with the amended indenture. Beginning with the quarter ending March 31, 2027, available cash exceeding a $500.0mn liquidity threshold is applied through the DBS Cash Sweep to redeem those notes at par.
- The $1.0bn of 2028 Senior Notes and $1.5bn of 2029 Senior Notes likewise remain outstanding as amended notes, with accrued interest and other amounts due paid under their respective amended indentures.
The Plan assigns the four impaired DBS note classes estimated recoveries of 100%, but those recoveries are not equivalent to immediate cash payment of principal. With the exception of amounts already redeemed or otherwise paid, holders receive amended securities corresponding to their allowed claims, and the Disclosure Statement cautions that the market value and liquidity of those securities are uncertain and that they may not trade at or near par. DBS general unsecured claims in Class 1H, DBS intercompany claims in Class 1I and interests in the DBS Debtors in Class 1J are unimpaired and presumed to accept the Plan.
The Plan separately preserves the approximately $8.856bn DWLLC Intercompany Loan Claim assigned before bankruptcy to the DWLLC Claims Trust for the benefit of holders of the 2028 Senior Secured Notes, 2028 Senior Notes and 2029 Senior Notes. Confirmation of the DBS Plan does not alter, satisfy, discharge or otherwise affect that separate claim against DWLLC, which remains disputed and will be treated exclusively through the DISH Wireless cases. The Plan and Confirmation Order make no representation that the Claims Trust will receive any recovery.
If the DWLLC Claims Trust ultimately receives distributions, the RSA waterfall continues to govern their use. Recoveries up to $300.0mn are applied among the three beneficiary note series at their applicable optional redemption prices; amounts above $300.0mn are first applied to redeem outstanding 2028 Senior Secured Notes at par, with any remaining proceeds after those notes are satisfied applied pro rata to the 2028 Senior Notes and 2029 Senior Notes at par. Any recovery through the Claims Trust is separate from the treatment noteholders receive directly from the DBS Debtors and, for the 2028 secured notes, from the DBS Cash Sweep.
The confirmed Plan also retains the affirmative opt-in structure for third-party releases. Creditors not otherwise bound under the RSA grant the releases only if they affirmatively elected to do so, and Epiq reported that 2,164 parties opted in by the September 23rd deadline. The Confirmation Order separately preserves causes of action against DBS general unsecured creditors that are not released parties and protects claims and rights belonging to the DISH Wireless Debtors and their estates, reinforcing the separation between the confirmed DBS restructuring and the unresolved Wireless cases.
The DBS-only financial projections appended to the September 4th Disclosure Statement cover October 2026 through December 2030 and assume approximately $525.0mn of opening cash. They project $2.221bn of revenue, $534.0mn of OIBDA and $337.0mn of operating cash flow for the final three months of 2026, followed by declining annual revenue from $8.160bn in 2027 to $6.958bn in 2030 and OIBDA declining from $2.081bn to $1.720bn. Operating cash flow remains positive throughout the period, while ending cash is projected at $1.164bn in 2027, $143.0mn in 2028, $1.299bn in 2029 and $2.407bn in 2030. The projections assume refinancing of the $1.0bn of 2028 Senior Notes and $1.5bn of 2029 Senior Notes at a 10% interest rate with maturities extending beyond 2030.
Those projections were prepared before the confirmation record reflected the additional redemption of the 2026 Senior Secured Notes: the Disclosure Statement projections assumed approximately $750.0mn of that series would remain to be repaid during the fourth quarter, while John Swieringa‘s September 27th confirmation declaration states that $2.35bn of the original $2.75bn had already been redeemed, leaving approximately $400.0mn of principal. The confirmation materials reviewed do not contain revised financial projections incorporating that later redemption.
The four impaired note classes overwhelmingly accepted the Plan, with more than 98% in number and 99% in amount of voting claims supporting confirmation. Class 1C accepted unanimously; Classes 1D and 1G accepted by more than 99.9% in amount; and Class 1F accepted by 93.28% in amount and 93.71% in number. Judge Lopez confirmed the Plan on September 29th, approved the amended note indentures and other Plan Supplement documents and waived the 14-day stay of the Confirmation Order, allowing the Debtors to proceed toward their targeted October 1st Effective Date.
From the Filings
The memorandum of law in support of confirmation of Debtors joint prepackaged Plan of Reorganization [Docket No. 1610] provides, “The DBS Plan is the product of extensive, arm’s-length prepetition negotiations among the DBS Debtors and their key economic stakeholders, which culminated in execution of the Restructuring Support Agreement (the ‘RSA’) as of March 19, 2026. Pursuant to the RSA, holders of more than 88% in aggregate principal amount outstanding under the DBS Notes (the ‘Consenting Creditors’) agreed to support a value-maximizing restructuring on the terms embodied in the DBS Plan. That broad-based consensus is reflected in the voting results. The DBS Plan has been approved by the votes of more than 98% in aggregate number (2,357 of 2,402 votes cast) and 99% in aggregate amount of voting Claims in the four Classes entitled to vote to accept or reject the DBS Plan (the ‘Voting Classes’):
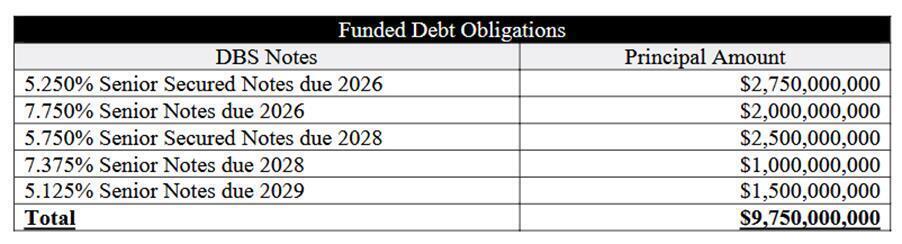
The extraordinary support for the DBS Plan underscores that its terms reflect a fair and reasonable compromise among the DBS Debtors’ stakeholders—not a contested outcome imposed on any constituency—and should be confirmed.”
The Modified Disclosure Statement [Docket No. 1344] explains, “To ensure that the DBS Debtors emerge from chapter 11 before the October 28, 2026 outside date specified in the Restructuring Support Agreement, the Debtors determined to bifurcate the Plan from the DISH Wireless Plan into separate joint plans for which the Debtors will pursue confirmation on separate tracks.
The Plan is proposed by the DBS Debtors and provides for the treatment and resolution of all outstanding Claims against, and Interests in, each of the DBS Debtors. Distributions to Holders of Allowed Claims or other Claims or Interests, as applicable, against the DBS Debtors shall be funded from (a) Cash on hand and (b) the issuance of and distribution of Amended Notes.
The claims asserted against DWLLC in respect of the DWLLC Intercompany Loan are disputed in DWLLC’s Chapter 11 Case and no representation or warranty is made that there will be any distributions or recovery in respect of the DWLLC Intercompany Loan.”
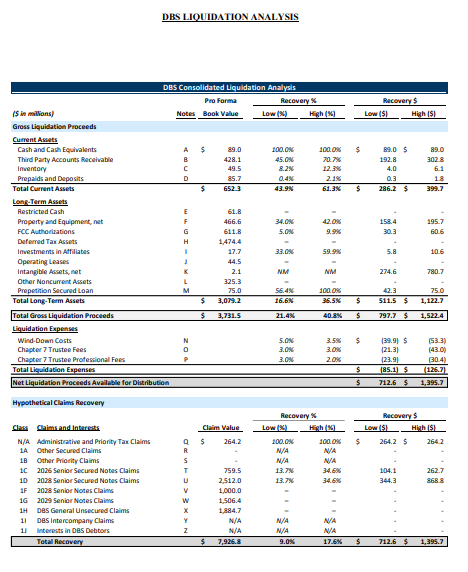
The following is a summary of classes, claims, voting rights and expected recoveries (defined terms not otherwise defined below, are as defined in the Plan and/or Disclosure Statement, also see the Liquidation Analysis below):
Classes of Claims against and Interests in the DBS Debtors
- Class 1A (“Other Secured Claims”) is unimpaired, presumed to accept and not entitled to vote on the Plan.
- Class 1B (“Other Priority Claims”) is unimpaired, presumed to accept and not entitled to vote on the Plan.
- Class 1C (“2026 Senior Secured Notes Claims”) is impaired and entitled to vote on the Plan. The estimated amount of claims is $759.5mn and the estimated recovery is 100%. Each holder of a claim shall receive (A) Amended 2026 Senior Secured Notes in a principal amount equal to the amount of such Holder’s Allowed 2026 Senior Secured Notes Claim on account of the unpaid principal amount of the 2026 Senior Secured Notes outstanding as of the Effective Date and (B) Cash in the amount of such Holder’s Allowed 2026 Senior Secured Notes Claim on account of any accrued and unpaid interest and any other amounts due and owing under the 2026 Senior Secured Notes Indenture as of the Effective Date; provided that accrued and unpaid interest included in the Allowed 2026 Senior Secured Notes Claim, but not yet due and owing under the 2026 Senior Secured Notes Indenture as of the Effective Date, will not be included in the principal amount of the Amended 2026 Senior Secured Notes, but instead will be paid in full in accordance with the Amended 2026 Senior Secured Notes Indenture and Amended 2026 Senior Secured Notes on the next scheduled semiannual interest payment date to Holders of record of the Amended 2026 Senior Secured Notes.
- Class 1D (“2028 Senior Secured Notes Claims”) is impaired and entitled to vote on the Plan. The estimated amount of claims is $2.512bn and the estimated recovery is 100%. Each holder of a claim shall receive (A) Amended 2028 Senior Secured Notes in a principal amount equal to the amount of such Holder’s Allowed 2028 Senior Secured Notes Claim on account of the unpaid principal amount of the 2028 Senior Secured Notes outstanding as of the Effective Date and (B) Cash in the amount of such Holder’s Allowed 2028 Senior Secured Notes Claim on account of any accrued and unpaid interest and any other amounts due and owing under the 2028 Senior Secured Notes Indenture as of the Effective Date; provided that accrued and unpaid interest included in the Allowed 2028 Senior Secured Notes Claim (but not yet due and owing under the 2028 Senior Secured Notes Indenture) as of the Effective Date will not be included in the principal amount of the Amended 2028 Senior Secured Notes, but instead will be paid in full in accordance with the Amended 2028 Senior Secured Notes Indenture and Amended 2028 Senior Secured Notes on the next scheduled semiannual interest payment date to Holders of record of the Amended 2028 Senior Secured Notes in accordance with the terms of the Amended 2028 Senior Secured Notes Indenture and Amended 2028 Senior Secured Notes. For the avoidance of doubt, (a) the separate DISH Wireless General Unsecured Claim held by the DWLLC Claims Trust under the DWLLC Intercompany Loan assigned to the DWLLC Claims Trust prior to the Petition Date for the ratable benefit of each DWLLC Claims Trust Beneficiary that is a Holder of an Allowed 2028 Senior Secured Notes Claim (and Holders of Allowed 2028 Senior Notes Claims and Allowed 2029 Senior Notes Claims) is a claim against DWLLC classified and treated exclusively under the DISH Wireless Plan, and shall be preserved and treated solely in accordance with that DISH Wireless Plan, subject to Article VI.E. of this Plan, and (b) such claim is disputed in DWLLC’s Chapter 11 Case and no representation or warranty is made that there will be any distributions or recovery in respect of such claim and all Persons and Entities have reserved their rights with respect thereto.
- Class 1E is reserved. The DBS Debtors have eliminated Class 1E because DBS repaid the 7.75% Senior Notes due 2026 issued by DBS, including the $2.0 billion in aggregate principal amount outstanding thereunder plus all accrued and unpaid interest to and including July 28, 2026 (the date of such repayment), pursuant to the Order (I) Authorizing the DBS Debtors to Pay All Amounts Outstanding under DBS’s 2026 Senior Notes and (II) Granting Related Relief [Dkt. No. 589] (the “2026 Senior Notes Pay All Order”).
- Class 1F (“2028 Senior Notes Claims”) is impaired and entitled to vote on the Plan. The estimated amount of claims is $1.0bn and the estimated recovery is 100%. Each holder of a claim shall receive (A) Amended 2028 Senior Notes in a principal amount equal to the amount of such Holder’s Allowed 2028 Senior Notes Claim on account of the unpaid principal amount of the 2028 Senior Notes outstanding as of the Effective Date and (B) Cash in the amount of Holder’s Allowed 2028 Senior Notes Claim on account of any accrued and unpaid interest and any other amounts due and owing under the 2028 Senior Notes Indenture as of the Effective Date; provided that accrued and unpaid interest included in the Allowed 2028 Senior Notes Claim (but not yet due and owing under the 2028 Senior Notes Indenture) as of the Effective Date will not be included in the principal amount of the Amended 2028 Senior Notes, but instead will be paid in full in accordance with the Amended 2028 Senior Notes Indenture and Amended 2028 Senior Notes on the next scheduled semiannual interest payment date to Holders of record of the Amended 2028 Senior Notes in accordance with the terms of the Amended 2028 Senior Notes Indenture and Amended 2028 Senior Notes. For the avoidance of doubt, (a) the separate DISH Wireless General Unsecured Claim held by the DWLLC Claims Trust under the DWLLC Intercompany Loan assigned to the DWLLC Claims Trust prior to the Petition Date for the ratable benefit of each DWLLC Claims Trust Beneficiary that is a Holder of an Allowed 2028 Senior Notes Claim (and Holders of Allowed 2028 Senior Secured Notes Claims and Allowed 2029 Senior Notes Claims) is a claim against DWLLC classified and treated exclusively under the DISH Wireless Plan, and shall be preserved and treated solely in accordance with that DISH Wireless Plan, subject to Article VI.E. of this Plan, and (b) such claim is disputed in DWLLC’s Chapter 11 Case and no representation or warranty is made that there will be any distributions or recovery in respect of such claim and all Persons and Entities have reserved their rights with respect thereto.
- Class 1G (“2029 Senior Notes Claims”) is impaired and entitled to vote on the Plan. The estimated amount of claims is $1.506bn and the estimated recovery is 100%. Each holder of a claim shall receive(A) Amended 2029 Senior Notes in a principal amount equal to the amount of such Holder’s Allowed 2029 Senior Notes Claim on account of the unpaid principal amount of the 2029 Senior Notes outstanding as of the Effective Date and (B) Cash in the amount of such Holder’s Allowed 2029 Senior Notes Claim on account of any accrued and unpaid interest and any other amounts due and owing under the 2029 Senior Notes Indenture as of the Effective Date; provided that accrued and unpaid interest included in the Allowed 2029 Senior Notes Claim (but not yet due and owing under the 2029 Senior Notes Indenture) as of the Effective Date will not be included in the principal amount of the Amended 2029 Senior Notes, but instead will be paid in full in accordance with the Amended 2029 Senior Notes Indenture and Amended 2029 Senior Notes on the next scheduled semiannual interest payment date to Holders of record of the Amended 2029 Senior Notes in accordance with the terms of the Amended 2029 Senior Notes Indenture and Amended 2029 Senior Notes. For the avoidance of doubt, (a) the separate DISH Wireless General Unsecured Claim held by the DWLLC Claims Trust under the DWLLC Intercompany Loan assigned to the DWLLC Claims Trust prior to the Petition Date for the ratable benefit of each DWLLC Claims Trust Beneficiary that is a Holder of an Allowed 2029 Senior Notes Claim (and Holders of other Allowed 2028 Senior Notes Claims and Allowed 2028 Senior Secured Notes Claims) is a claim against DWLLC classified and treated exclusively under the DISH Wireless Plan, and shall be preserved and treated solely in accordance with that DISH Wireless Plan, subject to Article VI.E. of this Plan, and (b) such claim is disputed in DWLLC’s Chapter 11 Case and no representation or warranty is made that there will be any distributions or recovery in respect of such claim and all Persons and Entities have reserved their rights with respect thereto.
- Class 1H (“DBS General Unsecured Claims”) is unimpaired, presumed to accept and not entitled to vote on the Plan.
- Class 1I (“DBS Intercompany Claims”) is unimpaired, presumed to accept and not entitled to vote on the Plan.
- Class 1J (“Interests in DBS Debtors”) is unimpaired, presumed to accept and not entitled to vote on the Plan.
Voting Results
Epiq Corporate Restructuring, LLC, a Vice President and Senior Consultant Stephenie Kjontvedt filed a declaration regarding the solicitation and tabulation of votes cast on the Debtors’ Second Modified Joint Prepackaged Chapter 11 Plan on September 27, 2026 [Docket No. 1607]. The voting results were as follows:
- Class 1C (“2026 Senior Secured Notes Claims”): 565 holders representing $2,626,871,809.00, or 100% by amount and 100% by number, voted to accept the Plan. None of the holders voted to reject.
- Class 1D (“2028 Senior Secured Notes Claims”): 615 holders representing $2,346,775,680.00, or 99.998% by amount and 99.84% by number, voted to accept the Plan. 1 holder representing $45,000, or 0.002% by amount and 0.16% by number, voted to reject.
- Class 1F (“2028 Senior Notes Claims”): 626 holders representing $844,138,610.53, or 93.28% by amount and 93.71% by number, voted to accept the Plan. 42 holders representing $60,818,102.83, or 6.72% by amount and 6.29% by number, voted to reject.
- Class 1G (“2029 Senior Notes Claims”): 551 holders representing $1,323,263,726.50, or 99.998% by amount and 99.64% by number, voted to accept the Plan. 2 holders representing $30,001.75, or 0.002% by amount and 0.36% by number, voted to reject.
Epiq Corporate Restructuring, LLC excluded certain defective ballots from the tabulation, primarily because holders failed to indicate whether they voted to accept or reject the Plan, while other ballots were superseded by later received ballots or withdrawn. The declaration further noted that holders were permitted to opt into the Plan’s Third-Party Release provisions, and 2,164 parties affirmatively elected to opt in as of the September 23, 2026 deadline, including 2,157 elections submitted through ballots and seven submitted through opt-in release forms.
Key Documents
The modified Disclosure Statement [Docket No. 1344] attaches the following documents:
- Exhibit A: Modified Joint Prepackaged Chapter 11 Plan of DISH DBS Corporation and Certain of Its Subsidiaries
- Exhibit B: Restructuring Support Agreement
- Exhibit C: Financial Projections
- Exhibit D: Liquidation Analysis
- Exhibit E: Organizational Structure Chart
The Debtors filed a Plan Supplements [Docket Nos. 1491 and 1606, respectively] that attaches the following documents
Docket No. 1491
- Exhibit A: Schedule of Rejected Contracts and Leases
- Exhibit B: Amended Notes Indentures
- Exhibit C: Section 1129(a)(5) Disclosures
Docket No. 1606
- Exhibit A: Schedule of Rejected Contracts and Leases
- Exhibit A-1: Redline to Previously Filed Schedule of Rejected Contracts and Leases
- Exhibit B: Amended Notes Indentures
- Exhibit B-1: Redline to Previously Filed Amended Notes Indentures
Liquidation Analyses (See Exhibit D of Docket No. 1344-4, for notes)
Case Status
The Disclosure Statement details the events leading to the need to seek bankruptcy shelter. Those events began with the sustained contraction of the Debtors’ core Pay-TV business as consumers abandoned traditional channel bundles for streaming services. After peaking at more than 14.0mn subscribers in 2014, the Pay-TV segment recorded its first annual net subscriber loss in 2015 and subsequently lost approximately 7.3mn subscribers. Sling TV offset part of the decline, but its month-to-month model produced higher customer turnover and required continued marketing expenditures. At the same time, programming costs increased and negotiations with broadcasters became more contentious, at times resulting in temporary channel takedowns. DBS responded by reducing staffing and field operations, curtailing customer-acquisition spending and focusing on profitability from its remaining subscribers.
Following EchoStar’s December 2023 acquisition of DISH Network, the company pursued a series of transactions intended to improve liquidity and financial flexibility. Those transactions transferred approximately 3.0mn subscribers and the Sling entities outside the DBS restricted group and supported a $2.5bn SubscriberCo financing used principally to repay $2.0bn of notes due in November 2024. Certain noteholders challenged the transactions through litigation alleging indenture breaches and fraudulent transfers, adding another layer of uncertainty before the dispute was resolved through the March 2026 RSA. A proposed sale of DBS to DirecTV was also intended to address the mismatch between declining Pay-TV revenue and more than $10.0bn of debt, but did not produce the required refinancing solution.
DBS’s immediate liquidity problem arose when $2.0bn of unsecured notes came due on July 1, 2026. The company expected funds derived from EchoStar’s approximately $23.0bn spectrum sale to AT&T to support repayment, but regulatory delays prevented the transaction from closing before maturity, leaving DBS unable to repay the notes while continuing to meet ordinary-course obligations.
The DISH Wireless Debtors faced a separate collapse in their business model. After the FCC directed EchoStar to sell or forfeit spectrum licenses, EchoStar agreed to major sales to AT&T and SpaceX, leaving DISH Wireless unable to operate its facilities-based radio access network and without entitlement to the transaction proceeds. DWLLC then asserted force majeure and related defenses under thousands of tower, fiber and equipment contracts. Although it reached hundreds of settlements, counterparties filed more than 170 lawsuits asserting over $6.0bn of aggregate damages, including unpaid and future rent, equipment-removal costs and other network obligations that substantially exceeded DWLLC’s available assets.
Prepetition Indebtedness
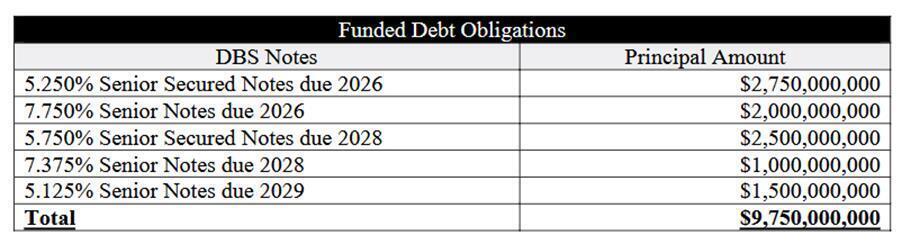
As of the date of this Disclosure Statement, the DBS Debtors have approximately $9.75bn in aggregate principal amount of funded debt obligations—i.e., the DBS Notes. Approximately $5.25bn in aggregate principal amount of DBS Notes are secured by substantially all of the DBS Debtors’ assets and approximately $4.5bn is unsecured. As of
the date hereof, the DBS Debtors have sufficient cash or cash equivalents and receivables to fund their operations in the ordinary course and pay restructuring expenses. The DBS Debtors do not anticipate needing any debtor-in-possession financing in these cases.
Funded Debt
- 5.250% Senior Secured Notes due 2026. DBS issued $2.75bn of 5.250% Senior Secured Notes under a November 2021 secured indenture, with Wilmington Savings Fund Society, FSB serving as successor trustee and U.S. Bank Trust Company, National Association serving as collateral agent. The notes mature on December 1, 2026 and are guaranteed by the other DBS Debtors. As of the Petition Date, the full $2.75bn principal amount remained outstanding.
- 7.750% Senior Notes due 2026. DBS issued $2.0bn of 7.750% Senior Notes under a June 2016 indenture, with Wilmington Savings Fund Society, FSB serving as successor trustee. The notes mature on July 1, 2026 and are guaranteed by the other DBS Debtors. As of the Petition Date, the full $2.0bn principal amount remained outstanding.
- 5.750% Senior Secured Notes due 2028. DBS issued $2.5bn of 5.750% Senior Secured Notes under a November 2021 secured indenture, with Wilmington Savings Fund Society, FSB serving as successor trustee and U.S. Bank Trust Company, National Association serving as collateral agent. The notes mature on December 1, 2028 and are guaranteed by the other DBS Debtors. As of the Petition Date, the full $2.5bn principal amount remained outstanding.
- 7.375% Senior Notes due 2028. DBS issued $1.0bn of 7.375% Senior Notes under a July 2020 indenture, with U.S. Bank Trust Company, National Association serving as trustee. The notes mature on July 1, 2028 and are guaranteed by the other DBS Debtors. As of the Petition Date, the full $1.0bn principal amount remained outstanding.
- 5.125% Senior Notes due 2029. DBS issued $1.5bn of 5.125% Senior Notes under a May 2021 indenture, with U.S. Bank Trust Company, National Association serving as trustee. The notes mature on June 1, 2029 and are guaranteed by the other DBS Debtors. As of the Petition Date, the full $1.5bn principal amount remained outstanding.
- DWLLC Intercompany Loan. Beginning in 2020, DNC advanced funds to DISH Wireless L.L.C. (“DWLLC”) to finance, among other things, construction of the 5G network. The parties memorialized those advances in an August 2025 loan agreement, with DNC serving as lender and DWLLC as borrower. The loan matures on November 30, 2030 and bears interest at 11.50%, generally payable in kind. As of June 28, 2026, approximately $8.8565bn was outstanding, inclusive of principal and accrued interest and after giving effect to $5.0bn of prior loan forgiveness. The agreement memorialized prior advances rather than establishing a conventional committed facility amount.
- Prepetition Secured Loan. DWLLC is party to an April 2026 $75.0mn secured term loan with DBS serving as lender. The facility matures on April 21, 2027, bears interest at 5.50% and is secured by substantially all of DWLLC’s assets, with DISH Wireless Leasing L.L.C. guaranteeing the obligations. As of the Petition Date, the full $75.0mn principal amount remained outstanding. Because both borrower and lender are Debtors, the facility is included only in the gross, nonconsolidated indebtedness calculation.
- DNC Notes Guarantee. DWLLC and DISH Wireless Leasing guarantee DNC’s $3.5bn of 11.75% Senior Secured Notes due 2027, issued under a November 2022 secured indenture with U.S. Bank Trust Company, National Association serving as trustee and collateral agent. DNC, rather than a Debtor, is the issuer and primary obligor. As of the Petition Date, the full $3.5bn principal amount remained outstanding, creating a contingent guarantee obligation against the two DISH Wireless Debtors. The attached documents identify the notes only as due in 2027 and do not provide the specific maturity date.
Unsecured Debt
In addition to the foregoing funded debt, the Plan projects approximately $1.8847bn of DBS general unsecured claims and between $9.0116bn and $13.9258bn of DISH Wireless general unsecured claims. The DISH Wireless estimate includes the $8.8565bn DWLLC Intercompany Loan described above, together with trade claims, contract and lease rejection claims and other unsecured liabilities, and therefore should not be added again when calculating aggregate indebtedness.
As of the date of the Disclosure Statement, the DBS Debtors also owed approximately $2.2bn to non-Debtor affiliates under shared-services arrangements, while the DISH Wireless Debtors owed approximately $3.7mn. These are affiliate reimbursement obligations rather than conventional third-party trade debt. About the Debtors DISH Network provides television entertainment and award-winning technology to millions of customers with its satellite DISH TV and streaming SLING TV services. In 2020, the company became a nationwide U.S. wireless carrier through the acquisition of Boost Mobile. DISH Network is a wholly owned subsidiary of EchoStar Corporation (NASDAQ: SATS). Organizational Structure Chart (See Exhibit E of Docket No. 7.6 for multi-page structure chart; simplified structure is as below)