
Bankruptcy Professional Spotlight
Jamie Sprayregen
by Zach Russell | Sep 23, 2026, 2:38:19 PM
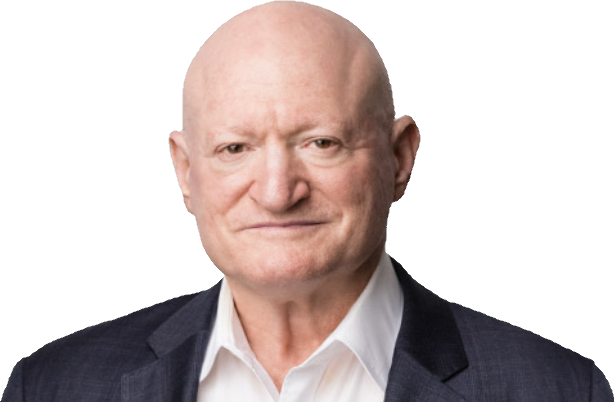
James H.M. "Jamie" Sprayregen has spent more than four decades in restructuring, working as counsel, investment banker, and senior advisor. He has since returned to private practice and now serves as co-head of Paul Weiss' Capital Solutions and Restructuring practice. Earlier in his career, he founded and built Kirkland & Ellis' restructuring practice into a global powerhouse, co-led the Restructuring Group at Goldman Sachs, and served as Vice Chairman, Global Strategy & Growth at Hilco Global.
Mr. Sprayregen has also served as President of INSOL International, was an adjunct professor at the Wharton School, is a Fellow of the American College of Bankruptcy, a member of the National Bankruptcy Conference, and a former member of the ABI Bankruptcy Reform Commission. He has advised on numerous high profile situations, including Energy Future Holdings, Seadrill Limited, Toys "R" Us, Caesars Entertainment, United Airlines, and Conseco.
We had the opportunity to speak with Mr. Sprayregen about why restructuring became what he calls the last bastion of the generalist, how he developed a reputation as a dealmaker while remaining willing to litigate, and the different perspectives his career journey has lent him. He also discussed the role of judgement in negotiations, the growth of the LME, the costs of Chapter 11, mass torts, and the forces likely to shape the future of restructuring.
Editor's Note: This interview has been edited and condensed. A PDF version of the interview is attached to this article.
Finding Restructuring
BankruptcyData: After you graduated from Illinois Law, you've said that you ended up in bankruptcy by accident and that you wanted to be a real estate lawyer. What made you stay?
SPRAYREGEN: That was in 1985, at Lord Bissel & Brook. They told me real estate wasn't too busy at the time and asked if I would work in bankruptcy. 40 years later and I'm still doing restructuring.
I found it intellectually interesting. The reason I stayed was that I found it to be the last bastion of the generalist. There is a process overlaid on the problem in the situation. It makes it interesting to become a subject matter expert in that area because you get to learn something different about different industries. When you put those things together, it makes it interesting.
Because it's not just litigation, I was able to meet lots of people within my own firm and all around the deal, other lawyers, bankers, and the C-suite. Working across industries kept it interesting.
BankruptcyData: Were there any particular people, cases, or moments early in your career that shaped the way you approach restructuring today?
SPRAYREGEN: There wasn't one seminal person. I took lots of little things from other people that worked for them. I do remember Leonard Rosen. He was incredibly substantive, and he conducted himself in a way where he could disagree without being disagreeable. I modeled the way he conducted himself.
Another interesting aspect of restructuring is you're a deal guy, but you're also in court. Ultimately, even though you need to be adept at both, your personal brand would either be first step deal or litigate. I wanted my personal brand to be a dealmaker. That helped get deals done, but you can't be afraid to litigate.
You also need leadership. Restructuring is a proactive, contact sport. Especially on the company side, many clients haven't been through the process before. Leadership, proactivity, and gaining the confidence of the client are important.
Building Teams and Advising Clients
BankruptcyData: When you look back at the early years of building Kirkland's restructuring practice, what do you think made you effective as a leader and allowed the group to grow?
SPRAYREGEN: I had the view that you need to be a subject matter expert and provide top notch expertise. As you develop that, to build the business, you had to empower younger people and provide guidance and learning opportunities. If you can develop 10 or 20 people, you can do more deals.
BankruptcyData: As the practice grew, how did you approach developing younger professionals? What did you find teachable, and what did people have to learn through experience?
SPRAYREGEN: I always quote Coach K: "You can't teach height." I can't tell someone to be smarter or to have better judgement. I can tell people to be a subject matter expert and to provide A-plus service, and to be responsive. They can watch how things are done and learn from that. As I said, restructuring is a contact sport and those are all teachable things.
If a deal goes bad, I like to do a lessons learned, and I do the same when it goes well. If you can sit back and ask what could we do better, I think there are huge opportunities to learn.
I would also say you have to be lucky, but you have to put yourself in a position to be lucky. You can sit in your office with the door closed, but you are more likely to be lucky when you are delivering good service.
BankruptcyData: You've now spent some time outside private practice at both Goldman and Hilco. What did seeing restructuring from those lenses teach you that you don't think you could have learned solely as a lawyer?
SPRAYREGEN: I taught at Wharton and Penn Law for a number of years, and I would get asked, 'Is it better to be a lawyer or a banker?' It's not such a bad thing to be a lawyer before being a banker or a banker before being a lawyer. What helped me is what I called touching a different part of the elephant. At Goldman, I did similar types of deals, but I was touching a different part of the elephant. I was actually the client, receiving the product and deciding whether I was getting good service. It was a good experience being the client. I learned a ton about things that would help me be a better lawyer.
A huge part of my time at Hilco was spent doing a major M&A transaction. We had a banker representing us, and for the first year we didn't involve lawyers. I met with dozens of prospective investors and buyers and spent a lot of time around people around the deal. I learned a lot. All of those things are part of the journey. Shame on me if I don't learn something at every stage. It helps me be a better lawyer.
BankruptcyData: How do you decide when compromise creates more value than continuing to fight?
SPRAYREGEN: The goal is to understand risk and the price of the risk, both in dollar terms and conditions of what the documents say. You also need to understand when there is too much risk and you walk away. Understanding that whole dynamic, and making sure the client understands the risk, helps you decide when to compromise and when not to.
I'm not a last penny negotiator, but I pay attention to the important things and decide where to let things go. Then there are the nice-to-have and must-haves. Those are judgement calls, and different clients have different perspectives on that. You have to take all of those things into account and add up the pluses and minuses.
BankruptcyData: How do you account for the personal side of restructuring while making difficult economic and legal decisions?
SPRAYREGEN: It's important sometimes to distinguish between the institution and the client, and to understand how that person came to sit where they are. Where you stand depends on where you sit. Is there employment risk? Those are not always knowable things, but understanding personal motivation is very helpful.
That applies to the constituencies around the table. Trying to read those considerations and having empathy and understanding is an important driver of getting things done.
Courts and Capital Solutions
BankruptcyData: Large Chapter 11 cases seem to have become concentrated in a small number of courts. How do you view that concentration?
SPRAYREGEN: Over my career, I have appeared in different courts around the country. In the vast majority of situations, I have been very impressed by the quality of the bench. I have never been a buyer of the proposition that you cannot do big cases without extensive prior experience. Many judges handle those situations very well. You do hear the argument about concentration. Obviously, experience is a benefit and can be helpful, but there is a lot of quality around the country.
BankruptcyData: When you evaluate an LME, what tells you whether it is fixing the capital structure versus just buying a year or two?
SPRAYREGEN: I always talk about it as if you were an MLB player. If you make an out 7 out of 10 times, you are still in the Hall of Fame. LMEs buy time and present an opportunity to potentially solve the problem. Just because you don't doesn't mean the transaction was not worth trying. You can use an LME to extend time, and if the company solves the problem, that's great. But if not, it's still the right thing to try. Being in a hurry to file is not heroic. If there's an opportunity, it makes sense to look at the alternatives. I think that is where the market has gone and why the Paul Weiss group is called Capital Solutions & Restructuring. An LME is still less risky than filing. I want to be more a deal maker than a litigator, and it's kind of the same thing. I think the first step is 'is there a capital solution that addresses part of the problem?' and looking at viable alternatives.
BankruptcyData: Has the restructuring lawyer's job fundamentally changed as a result of LMEs? Do you now have to think about competitive positioning among creditor groups much earlier than you would have 10 or 15 years ago?
SPRAYREGEN: I think that's treating LMEs with a broad brush. They range from fully consensual to very adversarial, and those transactions have evolved. A lot of what has been done has been done before. There is a premium on understanding the documents. Depending on the situation and what side of the table you are on, you are using your best judgement on how aggressive to be. There is a premium on understanding the facts and alternatives and coming up with the best direction and course possible.
BankruptcyData: Do you think we're seeing a bifurcation where traditional Chapter 11 increasingly works best for large companies that can afford a sophisticated restructuring process, while smaller companies have fewer viable options?
SPRAYREGEN: Going back all the way to when the 1978 Code went into effect, Congress wanted a very transparent process. But, there is a lot of paperwork and disclosure involved, and the company bears the burden of those costs. It's not surprising that people can figure out how to opt out of Chapter 11 through an LME that works for another non-court alternative. Those can be very efficient, save money, and protect value.
There is more and more pressure, as costs have increased, to look hard at what those alternatives are and to take advantage of them if they are available. Assuming if an LME isn't possible, it is critically important to live and breathe and understand what would happen in Chapter 11. It's not totally knowable, but understanding helps the negotiation. In the back of your head, you have a view of what happens and you are handicapping that against an LME alternative.
BankruptcyData: Bankruptcy has also become an increasingly important forum for resolving mass tort liabilities. Do you think courts are institutionally well suited to resolving those disputes?
SPRAYREGEN: I think you need to divide the question between the policy matter and the way the Code is written. As a policy matter, I think a forum for a global resolution makes a lot of sense for everyone. Bankruptcy is a pretty good forum for figuring it all out, maximizing the value of the enterprise, and getting fair compensation to victims. As a policy matter, yes, it makes a lot of sense.
As a legal matter, the Code is what it is at the present time. There are some changes in the Code that would make it easier to execute the policy. Those issues will continue to be debated as a matter of law.
On the Market
BankruptcyData: What developments are most likely to change the restructuring practice over the next five years?
SPRAYREGEN: I think the trends in the industry are more evolutionary than revolutionary. We will see more LMEs. Private credit hasn't gone through a credit cycle. There is also AI and its development and impact, and a macroeconomic environment that's been benign for a period of time. I don't think we have eliminated the credit cycle or the business cycle. You have all of those things swirling about, so there will be changes. You also have macro and geopolitical events too.
BankruptcyData: What do you like to do for fun?
SPRAYREGEN: I like to spend time with my kids and grandchildren. I'm a skier, a runner, and a reader.
Looking Ahead
Over more than four decades in restructuring, Jamie Sprayregen has seen the industry from nearly every side of the table – as a lawyer, banker, advisor, teacher, and client. Through each chapter, one principle has remained consistent: understand the facts, understand the people, and exercise good judgement.
As restructuring continues to evolve – through the growth of liability management exercises, private credit, new technologies, and the inevitable return of the credit cycle – that combination of experience, perspective, and adaptability may matter more than ever.