
B&G Foods, Inc. (NYSE: BGS) 2Q26 Tear Sheet
by Qi Huang | Oct 16, 2026, 6:53:00 PM
B&G Foods, Inc. (NYSE: BGS) is a branded packaged-food manufacturer working to reduce debt and reshape a portfolio built through years of acquisitions. The company owns established grocery brands including Crisco, Ortega and Cream of Wheat, but declining consumer demand and elevated borrowing costs have complicated its efforts to improve profitability. B&G is shifting away from lower-margin, capital-intensive businesses toward brands with stronger cash flow potential, while seeking to stabilize sales across its remaining portfolio.
In March 2026, B&G sold its Green Giant U.S. frozen business to reduce seasonal working capital requirements and acquired College Inn and Kitchen Basics to expand its broth and stock portfolio. The company also established a contract-manufacturing operation for the divested frozen business, which generated $23.9 million in second-quarter sales but remains only modestly profitable. The termination of the planned Canadian Green Giant sale in October removed another potential source of divestiture proceeds.
The broader packaged-food industry faces persistent pressure as price-sensitive consumers shift toward private-label products and lower-cost alternatives. Higher commodity and packaging costs further limit manufacturers' ability to protect margins without raising prices and risking additional volume losses. These conditions present a particular challenge for B&G as it attempts to stabilize its remaining businesses while managing substantial debt.
B&G has extended its debt maturities but faces higher interest costs and elevated leverage. With organic sales under pressure, meaningful debt reduction will depend on stronger cash generation and sustained improvements in its remaining brands.
About the Company
B&G Foods, Inc. (NYSE: BGS) is a manufacturer and distributor of branded shelf-stable and frozen foods and household products, founded in 1889 and headquartered in Parsippany, New Jersey. The company operates primarily in the United States, Canada and Puerto Rico through four business segments:
- Specialty: Offers cooking oils, baking ingredients, fruit spreads, canned foods, snacks and other specialty products. Key brands include Crisco, Clabber Girl, Bear Creek, Polaner, Underwood, B&G, Grandma's, New York Style, B&M and Baker's Joy.
- Meals: Produces packaged meal ingredients and convenience foods, including cereals, broths, stocks, Mexican-style sauces, taco products, pasta sauces and pizza crusts. Brands include Ortega, Cream of Wheat, College Inn, Kitchen Basics, Maple Grove Farms, Las Palmas, Victoria and Mama Mary's.
- Frozen & Vegetables: Operates frozen vegetable manufacturing facilities in Mexico that provide contract manufacturing services following the March 2026 sale of its Green Giant U.S. frozen business. The segment also includes the Green Giant and Le Sueur brands in Canada.
- Spices & Flavor Solutions: Produces spices, seasonings, sauces and flavoring products under brands including Dash, Spice Islands, Weber, Ac'cent, Tone's, Trappey's, Durkee and Wright's.
Capital Structure
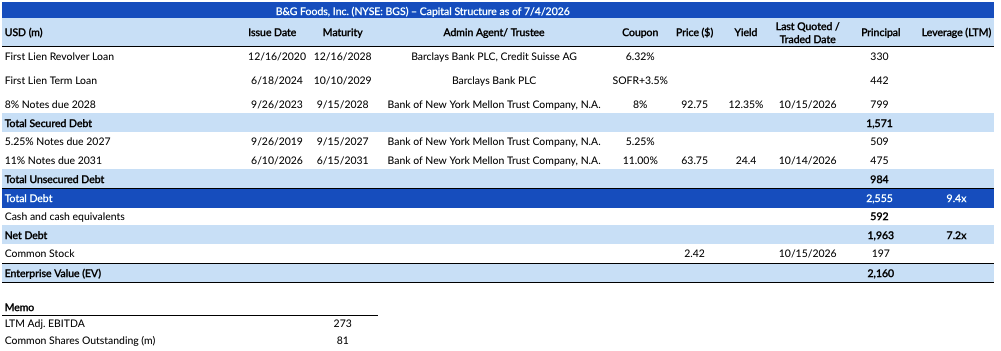
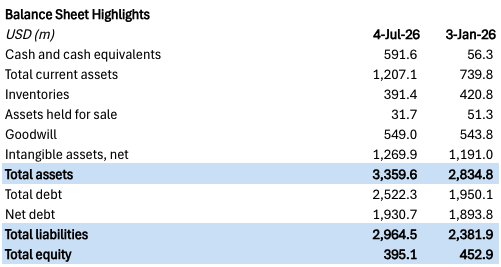
As of July 4, 2026, B&G Foods had approximately $2.56 billion of outstanding debt principal, including $1.57 billion of secured debt and $984 million of unsecured notes. The balance included both its $509.3 million of 5.25% notes due 2027 and newly issued $475 million of 11.00% notes due 2031. On July 6, the company redeemed the 2027 notes using proceeds from the new issuance, revolver borrowings and cash on hand. The refinancing extended maturities but increased annual interest costs. Based on LTM adjusted EBITDA of approximately $273 million, gross and net leverage were 9.4x and 7.2x, respectively, as of July 4, before the redemption. The reported $591.6 million cash balance was temporarily elevated by proceeds from the new notes.
Financial Highlights
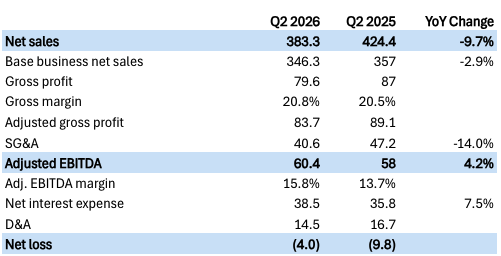
- Revenue Decline: Net sales fell 9.7% to $383.3 million, primarily reflecting divestitures, including Green Giant U.S. frozen. Base business sales declined 2.9% as volumes fell 4.3%, partially offset by favorable pricing and product mix. Management estimated that holiday-related shipping disruptions reduced quarterly sales by $5 million to $7 million.
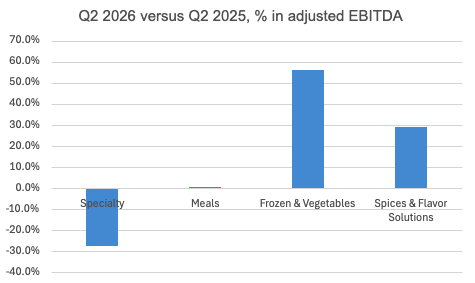
- EBITDA Improvement: Adjusted EBITDA rose 4.2% to $60.4 million, with margins expanding to 15.8% from 13.7%, benefiting from portfolio changes, lower overhead costs and tariff refunds. Spices & Flavor Solutions EBITDA increased 29.0%, while Specialty EBITDA declined 27.3% amid higher raw material and manufacturing costs.
- Net Loss and Interest Expense: Net loss narrowed to $4.0 million from $9.8 million, while net interest expense increased 7.5% to $38.5 million due to higher average debt balances, the 11.00% coupon on new notes and 24 days of overlapping interest during the refinancing.
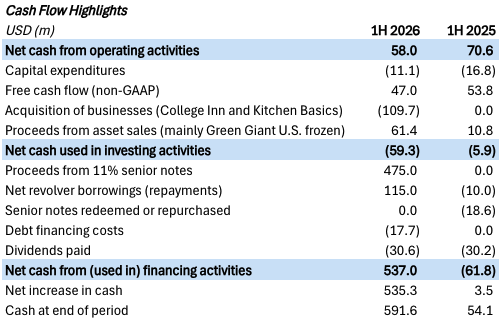
- Weaker Cash Generation: First-half operating cash flow declined to $58.0 million from $70.6 million, while free cash flow fell to $47.0 million from $53.8 million. The company received $61.4 million from asset sales but spent $109.7 million on acquisitions during the period.
- 2026 Outlook: Management reaffirmed adjusted EBITDA guidance of $275 million to $290 million and projected cash interest expense of $150 million to $155 million. Capital expenditures are expected at the lower end of the $30 million to $35 million target range.
Peer Review
Conagra Brands, Inc. (NYSE: CAG) is a Chicago-based packaged food company with frozen, refrigerated, and shelf-stable brands such as Birds Eye, Healthy Choice, Marie Callender’s, and Slim Jim. The Hain Celestial Group, Inc. (NASDAQ: HAIN) is a better-for-you food and beverage company whose brands include Celestial Seasonings tea, Earth’s Best baby food, and Greek Gods yogurt, and it is narrowing to a North American focus. The Campbell’s Company (NASDAQ: CPB) is a Camden, New Jersey-based maker of soups, sauces, snacks, and meals, with brands including Campbell’s, Prego, Rao’s, Goldfish, and Snyder’s of Hanover.
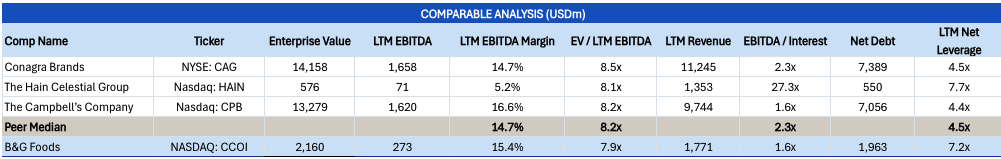
B&G Foods' 15.4% LTM EBITDA margin is slightly above the 14.7% peer median, while its 7.9x EV/EBITDA is below the 8.2x peer median. Net leverage of 7.2x as of July 4, before the redemption of its 2027 notes, significantly exceeds the 4.5x peer median. EBITDA interest coverage of 1.6x is tied with Campbell's for the weakest in the group. Refinancing the 2027 notes at a substantially higher coupon adds pressure to interest coverage, leaving debt reduction increasingly dependent on stronger operating cash flow.
| Company Name | Strategic Developments |
|
Conagra Brands (NYSE: CAG) |
Conagra is resetting toward margin recovery under new CEO John Brase, with its quarterly dividend cut in half and advertising spend rising about 14% in fiscal 2027, focused on frozen meals and meat snacks. Net debt fell 11.9% to $7.1 billion, a 3.83x net leverage ratio, against a long-term target of 3.0x, though most benefits from its Project Catalyst cost program are not expected until fiscal 2028. |
| The Hain Celestial Group (Nasdaq: HAIN) | Hain is becoming a focused North American business after selling its North American snacks unit and agreeing to sell its International business for about $323 million in cash, with proceeds earmarked for debt reduction. Fiscal 2026 net debt fell to $500 million from $650 million, and free cash flow improved to $58 million. The sale also addresses a December 2026 debt maturity. |
|
The Campbell’s Company (Nasdaq: CPB) |
Campbell’s is prioritizing debt reduction after cutting its quarterly dividend 36% to $0.25 and setting a $500 million cost-savings target by fiscal 2030. Net leverage rose to 4.3x from 3.6x a year earlier, with management aiming to return to roughly 3.0x, while continued weakness in Snacks and the La Regina investment weigh on near-term earnings. |